How to Claim Reimbursement from Private Insurance in Bulgaria
Alright, let's talk about something that can be a real headache for us expats in Bulgaria: dealing with private health insurance claims. You've navigated the often-confusing healthcare system, found a doctor, and perhaps even paid out-of-pocket, only to realize the next hurdle is getting your money back. This guide is here to walk you through the labyrinthine process of claiming reimbursement from your private health insurance, helping you understand each step so you can avoid common pitfalls and get what you're owed.
Understanding Your Private Insurance Policy in Bulgaria
Before you even think about submitting a claim, you absolutely must understand the ins and outs of your private health insurance policy. This isn't just bureaucratic fluff; it's the bedrock of a successful reimbursement. Many expats make the mistake of assuming all policies are the same or that their old policy from back home will magically cover everything in Bulgaria. That's rarely the case, and a quick read-through of your terms and conditions can save you immense frustration down the line.
Key Policy Components and Terms
Your policy document is a treasure trove of vital information, even if it reads like a legal textbook. Pay close attention to definitions, as terms like "acute condition," "pre-existing condition," and "elective procedure" can vary significantly between providers and might directly impact your claim's eligibility. For instance, a condition you consider acute might be classified as chronic by your insurer if it requires ongoing treatment. This distinction is paramount because chronic conditions often have different coverage limits or waiting periods.
Beyond definitions, you'll find details on your deductible (or excess), co-payment percentages, and overall annual limits. The deductible is the amount you have to pay yourself before your insurance kicks in. If your deductible is, say, €500, and your medical bill is €300, you won't get anything back from the insurance company for that specific incident. Co-payments, on the other hand, are a percentage of the bill you're always responsible for, even after meeting your deductible. Some policies might have a 10% co-payment for specialist visits, meaning if the visit costs 100 leva, you'll pay 10 leva out of your own pocket and the insurer covers the remaining 90, assuming your deductible has been met.
Coverage Limits and Exclusions
Every private insurance policy comes with limits and exclusions, and trust me, you want to know these before you need to use your insurance. Coverage limits dictate the maximum amount your insurer will pay for specific treatments, services, or even over the course of a year. For example, your policy might cover up to €1,000 for dental work annually, or have a €50,000 lifetime limit for a particular illness. Go over these limits with a fine-tooth comb, especially for services you anticipate needing, such as physiotherapy, mental health support, or even maternity care.
Exclusions are equally, if not more, important. These are the specific things your policy will not cover under any circumstances. Common exclusions include cosmetic procedures, experimental treatments, certain pre-existing conditions (especially if not declared or if there's a waiting period), self-inflicted injuries, or treatments for conditions arising from dangerous sports or activities. It’s also crucial to check if your policy has a geographic exclusion. Some policies, especially travel insurance like SafetyWing, are designed for specific durations or locations, and might have limitations on long-term residency or certain countries. Knowing these limitations beforehand prevents the crushing disappointment of a denied claim later on.
Preparing for Reimbursement: Before Your Appointment
The groundwork for a successful reimbursement claim often begins even before you step foot in a clinic. In Bulgaria, where direct billing with private international insurance can be less common outside of major international hospitals in Sofia, being proactive is your best friend. Don't wait until you're holding a bill to start thinking about your insurance. A little preparation can make a huge difference in how smoothly your claim proceeds.
Pre-Authorisation and Approval
For many significant medical procedures, hospital stays, or specialist treatments, your private insurance provider will require pre-authorisation. This means you need to get their approval before undergoing the treatment. Ignoring this step is a common reason for claims being partially or fully denied. Typically, your doctor or the clinic will need to submit a treatment plan, including estimated costs, to your insurance company. The insurer then reviews it to confirm it's medically necessary and covered under your policy.
Always ask your doctor if pre-authorisation is needed for a recommended procedure. If it is, ensure they provide you with all the necessary documents, often in English or translated, to send to your insurer. This process can take a few days, so factor that into your planning. For routine doctor visits or small emergencies, pre-authorisation is usually not required, but for anything substantial like surgery, extended therapy, or an MRI scan, it’s almost always a prerequisite. Some Bulgarian clinics and hospitals are well-versed in this process for international patients, but smaller practices might need some guidance from you.
Essential Documents to Collect on Site
This is where the real work begins when you're actually at the medical facility. Whether it's a quick visit to a GP or a more involved specialist appointment, you need to be diligent about collecting the right paperwork. Think of yourself as an administrative detective. The single most important document you'll need is a detailed medical report, often called an "epicrisis" (епикриза) for hospital stays, or a doctor's note (медицинска бележка) for outpatient visits. This report must clearly state your diagnosis, the treatment received, and the medical necessity for that treatment. Make sure it's signed and stamped by the attending physician and ideally, includes the doctor's license number.
Equally crucial are the original invoices and receipts for all services rendered and medications purchased. These need to be itemized, showing exactly what you paid for. If you visit a pharmacy, keep all prescription receipts. For consultations, ensure the invoice explicitly states the type of consultation (e.g., "consultation with cardiologist" rather than just "medical service"). Many Bulgarian clinics issue fiscal receipts (касов бон) for payment, which is good, but you'll also need a separate, more detailed invoice (фактура) or medical report that describes the services for insurance purposes. Don't be shy about asking for these details; it's your right, and your reimbursement depends on it. Ideally, these documents should be in English, or you may need to get them officially translated later, which adds cost and time.
The Step-by-Step Reimbursement Process
Once you've had your medical treatment and carefully collected all the required documents, it's time to actually submit your claim. While the exact steps might vary slightly depending on your private insurer, there's a general process that most follow. Being organised and methodical here will save you a lot of back-and-forth.
Completing the Claim Form
The first official step is usually to fill out your insurance provider's claim form. You can typically download this from their website. Don't rush through this. Read every question carefully and provide accurate, complete information. You'll need to fill in your personal details, policy number, the date and nature of the medical incident, the name and contact details of the healthcare provider in Bulgaria, and the total amount you are claiming. It's often tempting to leave sections blank if you're unsure, but this usually leads to delays or requests for further information.
If you have any doubts about a specific section, it’s always better to contact your insurer directly for clarification before submitting. Some claim forms might also have a section for the treating physician to complete. While this isn't always mandatory for every minor claim, if your policy specifically requests it, ensure your Bulgarian doctor fills it out and stamps it before you send it off. Remember, the clearer and more comprehensive your claim form is, the less likely it is to get held up in processing.
Attaching Supporting Documents
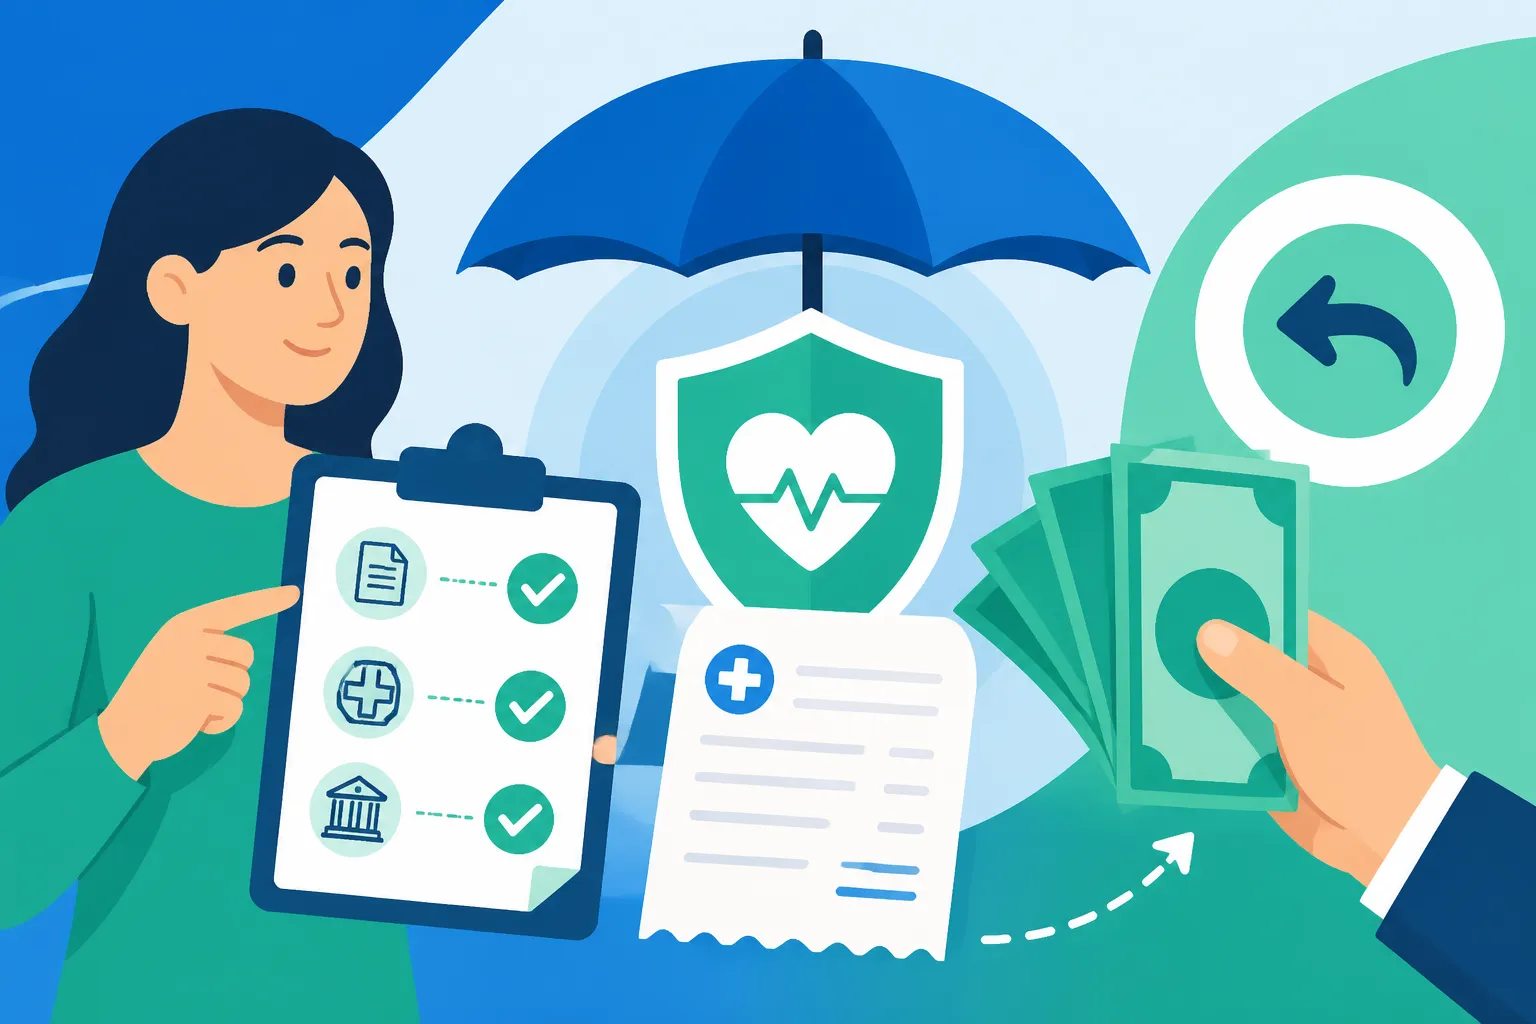
This is arguably the most critical part of the process. Your claim form is just a summary; the supporting documents are the evidence. You'll need to attach all the original invoices, receipts, and detailed medical reports you collected. For hospital stays, this includes the full epicrisis. For medication, attach the original pharmacy receipts and, if possible, a copy of the prescription. Any pre-authorisation approval letters you received should also be included.
It's absolutely vital to send copies of everything and keep the originals for your records. If your insurer insists on originals (some do for larger claims), make sure you've made clear, legible copies first. Always create a checklist of all documents you're submitting and use it to double-check before sending. Imagine the frustration of a claim being denied because you forgot one small piece of paper. If any documents are not in English, your insurer might require an official translation. While some might accept Bulgarian for common medical terms, be prepared for this additional step. Companies like SafetyWing often provide clear guidelines on language requirements.
Submitting Your Claim and Tracking Progress
Once everything is meticulously prepared, you can submit your claim. Most modern private insurers offer several submission methods:
- Online Portal: This is often the quickest and most efficient method. You upload scanned copies of your documents directly to your insurer's secure portal. You'll usually get an immediate confirmation of receipt and can track the status of your claim online.
- Email: Some insurers allow claims via email, especially for smaller amounts. However, ensure they provide an encrypted or secure email address for sensitive medical information.
- Mail: For those who prefer physical submission, or if your insurer requires original documents, traditional mail is an option. Always send it via registered post with a tracking number so you have proof of delivery.
After submission, patience is key, but don't be passive. Note down the claim reference number and keep an eye on its progress. If you don't hear anything within the expected timeframe (which your insurer should communicate), don't hesitate to follow up. A polite email or phone call to their claims department can sometimes nudge things along. Keep a record of all correspondence and phone calls, including dates, times, and the names of the people you spoke with. This documentation can be invaluable if any disputes arise.
Common Hurdles and How to Overcome Them
Dealing with insurance companies, especially across international borders, can feel like navigating a maze blindfolded. Many expats encounter similar frustrations, from language barriers to unexpected denials. Understanding these common hurdles beforehand can equip you to tackle them head-on, saving you stress and potential financial loss.
Language Barriers and Document Translation
Bulgaria is making great strides, but English isn't universally spoken, especially outside of major cities or modern, internationally-oriented clinics. This can become a significant issue when collecting medical reports and invoices. While some private hospitals in Sofia or Plovdiv might provide documents in English upon request, many smaller clinics and general practitioners will only issue them in Bulgarian. Your private insurer, especially if it's an international one, will almost certainly require documents to be in English or accompanied by a certified translation.
If you find yourself with Bulgarian-only documents, you'll need to seek out a sworn translator. The cost of translation is usually borne by you, although some premium insurance plans might cover it. Always ask for an official translation that includes the translator's stamp and signature, as this is what most insurers will accept. Don't try to use online translation tools for official documents; they won't cut it. To minimise this hurdle, it's worth asking for an English version of the medical report at the time of service. While not always possible, it's worth a try. Sometimes even a basic, handwritten note from the doctor in English explaining the diagnosis can help supplement official Bulgarian documents.
Navigating Deductibles and Co-Payments
These are the hidden costs that often surprise expats. A deductible is the initial amount you pay out-of-pocket before your insurance starts contributing. For example, if your policy has a €250 deductible, you'll pay the first €250 of your medical expenses each policy year before any reimbursement is made. If your total claims for the year only amount to €200, you won't get any money back. Keep track of your medical expenses throughout the year to know when you've met your deductible.
Co-payments, on the other hand, are a percentage of the cost you're responsible for after your deductible has been met. This could be 10% for specialist visits or 20% for prescription medications. While seemingly small, these percentages can add up, especially for long-term treatments. Always clarify these figures with your insurer when you first take out the policy and keep them in mind when budgeting for medical care. Sometimes, people assume "private insurance" means 100% coverage from day one, which is rarely the case, particularly for basic plans or those designed for travellers like SafetyWing, which typically have lower coverage limits and higher deductibles suited for short-term stays.
Dealing with Denied Claims
A denied claim is disheartening, but it's not always the final word. The most common reasons for denial include:
- Lack of pre-authorisation: You didn't get approval for a procedure that required it.
- Missing or incomplete documents: A crucial invoice or medical report was omitted.
- Exclusion in policy: The treatment is explicitly not covered (e.g., cosmetic surgery, pre-existing condition).
- Exceeded limits: You've gone over the maximum coverage for a specific service or annually.
- Claim submitted too late: There's a strict timeframe for submitting claims.
If your claim is denied, the first step is to understand why. Your insurer is legally obligated to provide a reason. Review their explanation against your policy documents. If you believe the denial is incorrect, gather any additional evidence you have (e.g., a doctor's letter of medical necessity, a translation you forgot to include) and formally appeal the decision. Most insurance companies have a multi-stage appeals process. Be persistent, articulate your case clearly, and provide all supporting documentation. Remember, you have consumer rights, and understanding those can empower you during an appeal.
Specific Scenarios and Considerations
Healthcare needs aren't always straightforward, and certain situations in Bulgaria can add extra layers of complexity to the reimbursement process. Knowing how to approach these specific scenarios can save you a lot of grief and ensure you receive the maximum benefit from your private insurance.
Emergency Medical Care
Emergencies are, by their nature, unplanned. This means pre-authorisation often goes out the window. In a genuine medical emergency in Bulgaria, your priority should always be getting immediate treatment. Dial 112 for an ambulance or head straight to the nearest emergency room. Once the immediate crisis has passed, and you or a family member are able, inform your insurance company as soon as possible. Many policies have a clause requiring notification within 24-48 hours of an emergency admission or significant treatment. Failure to do so could impact your claim.
When it comes to documentation, be extra diligent after an emergency. Ensure you get a detailed medical report from the emergency department or hospital describing the diagnosis, treatment provided, and the medical necessity of the emergency intervention. This is particularly crucial because some insurers might dispute whether the situation truly constituted an emergency if the documentation is vague. Keep all receipts for ambulance services, emergency room fees, tests, and any medications administered during your stay. Even if you were unconscious or unable to collect documents at the time, request them from the hospital staff before you leave, or send a trusted friend or family member to do so. Understanding Emergency Medical Care in Bulgaria: What Every Expat Needs to Know can help prepare you for such situations.
Prescription Medications and Pharmacy Purchases
In Bulgaria, pharmacists are generally knowledgeable and accessible, and many common medications can be purchased over-the-counter or with a doctor's prescription. For your private insurance to reimburse prescription medications, you'll almost always need two things: the original pharmacy receipt and a valid prescription from a licensed Bulgarian doctor. The prescription serves as proof of medical necessity. Make sure the receipt clearly itemises the medication purchased, its quantity, and the price.
Some private policies have specific limits or co-payments for prescription drugs, so check your policy details. For ongoing medications, you might need to submit claims periodically. If you're importing a prescription from your home country, be aware that your Bulgarian private insurance is unlikely to cover it unless a local doctor has issued a corresponding Bulgarian prescription. It's always a good idea to discuss your long-term medication needs with your GP in Bulgaria to ensure seamless coverage and avoid issues when claiming.
Dental and Vision Care
Dental and vision care are often treated separately from general medical care in private insurance policies, and they frequently have their own, lower, annual limits and higher co-payments. Many basic private health insurance plans might not cover routine dental check-ups, cleanings, or glasses at all, only extending to emergency dental work (e.g., tooth extraction for severe pain). Comprehensive dental coverage is usually an add-on, or a feature of more premium plans.
If your policy does cover dental or vision, ensure you understand the specific benefits, such as the number of cleanings per year, coverage for fillings, crowns, or spectacles. Similar to other medical claims, you'll need an itemised invoice from your dentist or optometrist, detailing the services or products received, along with a medical report explaining the necessity of the treatment. For example, a note from the dentist stating "caries requiring filling" would be essential for a claim related to a filling. Always get a clear quote from the dental or vision professional before proceeding with significant work, and compare it against your policy's limits.
The Role of the National Health Insurance Fund (NHIF)
For many expats, especially those legally employed or self-employed in Bulgaria, understanding the interplay between their mandatory contributions to the National Health Insurance Fund (NHIF) and any supplementary private insurance is crucial. It’s not always an either/or situation; often, they can complement each other.
Public Versus Private: A Balancing Act
If you are legally working in Bulgaria, you are generally required to contribute to the NHIF. This provides you with access to public healthcare services, including a registered GP, specialist referrals, and hospital care, often with co-payments. However, the public system in Bulgaria can come with longer wait times for specialists, more basic facilities in some regions, and limited access to English-speaking medical staff. This is where private insurance often steps in, filling the gaps.
Many expats choose private insurance not to replace NHIF coverage, but to enhance it. Private plans can offer faster access to specialists, choice of doctors and hospitals (often private clinics with modern facilities), access to English-speaking medical professionals, and coverage for treatments or comforts not typically covered by the NHIF, such as private hospital rooms. The key is to understand what each covers. For example, if your NHIF covers a basic specialist visit, your private insurance might cover the "private" version of that visit or the co-payment. For a detailed comparison, see our guide on Public vs Private Healthcare in Bulgaria: What Expats Need to Know.
How Private Insurance Complements NHIF Coverage
Think of your private insurance as a safety net or an upgrade. When you have both, your private insurance can be used to cover the co-payments or services that the NHIF doesn't fully fund. For example, if you see a specialist referred by your NHIF GP, but you choose to see them at a private clinic for quicker access or better facilities, your private insurance can cover that cost, or at least a significant portion of it. Similarly, while the NHIF covers basic hospital stays, private insurance might cover the difference for a private room or additional amenities.
However, it's important to clarify with your private insurer how they handle claims when you also have NHIF coverage. Some policies might require you to first claim through the NHIF, and then your private insurance covers the remaining balance. Others might simply cover private treatment directly, without needing to involve the NHIF at all, as long as you use a private facility that doesn't operate under NHIF contracts. Always check your specific policy, as this dual-system navigation can be one of the trickiest aspects for foreigners. For more on the mandatory public system, refer to Understanding Mandatory Health Insurance Contributions in Bulgaria.
The Future of Claims and Digital Solutions
The landscape of insurance claims is constantly evolving, with a growing push towards digital solutions and greater transparency. For expats in Bulgaria, this can mean a smoother, more efficient process for getting reimbursed, provided you know how to leverage these tools.
Online Portals and Mobile Apps
Most major private insurance providers, whether international or local, now offer robust online portals and mobile apps. These platforms are designed to streamline the claims process significantly. Instead of printing forms and sending physical mail, you can often:
- Submit claims electronically: Upload scanned documents directly from your computer or phone.
- Track claim status: Monitor the progress of your claim in real-time.
- Access policy documents: View your policy terms, limits, and exclusions at any time.
- Find in-network providers: Some apps help you locate doctors and clinics that work with your insurer, though direct billing for international private insurance can still be limited in Bulgaria.
- Contact support: Communicate with customer service agents directly through secure messaging.
Embrace these digital tools. They not only speed up the process but also provide a clear, trackable record of all your interactions and submissions. Many expats find them invaluable, especially when dealing with time zone differences or language barriers over the phone. Companies that cater to digital nomads, such as SafetyWing, are particularly strong in this area, offering intuitive online platforms designed for easy access and claims submission from anywhere in the world.
Direct Billing vs. Reimbursement Explained
It's important to clarify the difference between direct billing and reimbursement, as this often causes confusion for expats.
Direct Billing (or Cashless Facility): This is the ideal scenario, where the hospital or clinic bills your insurance company directly. You don't pay anything out-of-pocket (beyond any co-payment or deductible specified in your policy) at the point of service. This is common in countries with highly integrated private healthcare systems or for large, international hospitals that have established agreements with major insurers. In Bulgaria, direct billing can happen, particularly at some of the larger private hospitals in Sofia like Acibadem City Clinic Tokuda Hospital or Hill Clinic, but it's not guaranteed for every private insurer or every medical facility. You usually need to check with your insurer AND the clinic beforehand.
Reimbursement: This is what we've been discussing throughout this guide. You pay for the medical service yourself at the time of treatment, and then you submit a claim to your insurance company to get your money back. This is the more common scenario for many private insurance policies in Bulgaria, especially for outpatient visits to smaller private clinics or specialist offices, and for pharmacy purchases.
Always ask your insurance provider and the medical facility whether direct billing is an option for your planned treatment. If it is, confirm the process: what documents do you need to provide to the clinic, and when? If not, then you're firmly in the reimbursement camp, and all the steps outlined in this guide become even more critical.
| Feature | Direct Billing (Cashless) | Reimbursement |
|---|---|---|
| Initial Payment | You pay nothing (or only co-pay/deductible) | You pay the full cost upfront |
| Administrative Burden | Less for you; clinic handles billing with insurer | More for you; you collect documents and submit claim |
| Waiting Time for Funds | None (funds go directly to clinic) | Varies (insurer processing time, typically 7-30 days) |
| Common Scenarios | Major hospitals with insurer agreements, planned surgeries | Outpatient visits, pharmacies, smaller clinics, emergencies |
| Pre-Authorisation | Often required by clinic and insurer | Often required by insurer for larger claims |
| Ease in Bulgaria | Limited to larger private hospitals for some insurers | More common for most private insurance scenarios |
Final Thoughts for Expats in Bulgaria
Navigating the healthcare system and then jumping through the hoops of insurance claims can be one of the most stressful parts of expat life in Bulgaria. It’s certainly not always smooth sailing, and you might encounter moments where you feel like giving up. But remember, with preparation, diligence, and a bit of persistence, you can significantly improve your chances of successful reimbursement.
Always keep your policy documents handy, ask questions at every stage (both to your doctor and your insurer), and maintain meticulous records. Knowing your rights and the typical processes will empower you. Whether it's a simple doctor's visit or a more complex medical event, being well-informed is your best defence against unexpected costs and administrative headaches. For more insights on financial aspects of healthcare, make sure to check out The Cost of Healthcare in Bulgaria: A Complete Breakdown for Foreigners.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional medical, legal, or insurance advice. While we strive to keep the information up-to-date and accurate, healthcare and insurance regulations in Bulgaria can change. Always consult directly with your private insurance provider and, if necessary, a legal or financial professional for advice tailored to your specific situation.